--%>

Problem on stock market

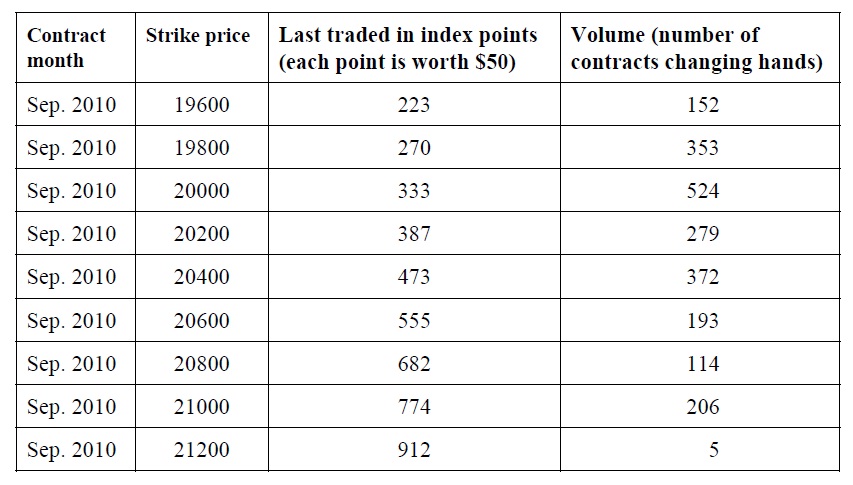
John Wong is a fresh graduate and has a limited amount of funds for investments. He expects that the Hong Kong stock market will fall soon but he is not familiar with derivatives. In order to gain more money to buy a car, he explores engaging in Hang Seng Index (HSI) options trading. After consulting his investment advisor, he considers HSI put options in the table below. As of the market closed on 24 August 2010, the Hang Seng Index was at 20659.

The information for Hang Seng Index put options as of 24 August 2010:
2466_stock market.jpg

a) After reading the above table, John Wong realizes that HSI put options are very expensive for higher strike price put options. Please explain.

b) John Wong observes that the lower strike price options have a higher trading volume than higher strike price options. Please explain this phenomenon.

c) John Wong decides to focus on the HSI put option with the 20600 strike price. He is, however, not sure about the fair market price of the option. If the dividend yield of HSI constituent stocks is 3%, the Hong Kong interbank offered rate is 1%, the standard deviation of the HSI index return is 0.22, and the option has, for simplicity, one month to expire, what is the fair value of the put option using the Black-Scholes option pricing model? Show all your steps. Is the option price calculated the same as the market price shown in the table? If not, please explain the reason.

d) Under the Black-Scholes option pricing model, which factor do you think is the most difficult one to estimate? Discuss two methods to estimate the above factor and explain which method is the best.

   Related Questions in Corporate Finance

  • Q : Explain Straddle and Strangle Straddle

    Straddle & Strangle: In the case of shorting butterfly spread, it can be seen that the gains are limited. However, there exists another strategy known as straddle which produces unlimited gains. This strategy benefits when the trader expects that

  • Q : Assessing market expectations using CAPM

    Assume that the risk-free rate is 1% and the expected market return is 9%. You are considering purchasing Super Soft stock, which currently sells for $100 a share and will pay its next (annual) dividend of $1.00 exactly one year from today. Super Soft is considered to

  • Q : Price per share for Corporation For XYZ

    For XYZ Corporation debt-to-equity ratio, marginal tax rate, and dividend payout ratio are all of 40%. The cost of debt is 10%. Cambria contains 1 million shares of common stock, and $25 million in long-term bonds. Its dividend is $1 per share. Determine the EBIT and

  • Q : Explain merits and demerits of standard

    Explain merits and demerits of standard market practice to find the volatility as a function of underlying.

  • Q : Who described option pricing with

    Who described option pricing with deterministic volatility?

  • Q : Problem on maintaining dividend Jackson

    Jackson Company has 6 million shares of common stock selling at $55 each. It also has $120 million in long-term bonds with coupon 7%, selling at 90. The tax rate of Jackson is 33%. Next year its EBIT is expected to be $25 million with a standard deviation of $7 millio

  • Q : Convertible Bonds-Corporate Bonds State

    State the term Convertible Bonds in Corporate Bonds?

  • Q : Difference between intrinsic value and

    XYZ explained the difference between intrinsic value and book value in terms of the money spent on a college education. Please provide another example using a different simile.

  • Q : What is Money Spreads Money Spreads :

    Money Spreads: Option trading strategies can be classified into various types like those pertaining to combination of one option with another option or set of options, other derivative contracts, stocks, etc. This paper focuses mainly on money spreads

  • Q : Financial engineering financial

    financial engineering examples,benifits,disadvantages