--%>

Problem on long run competitive equilibrium

The technology is such that LAC is minimized at firm’s output equivalent to 10 and minimum LAC is Rs. 15. Assume that the demand schedule for the product is given as shown:
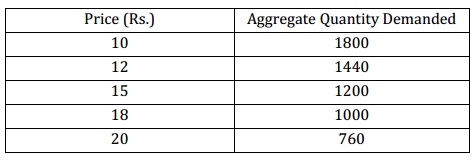
2207_table price.jpg

(i) Determine total quantity sold in market and how many firms will operate in long run competitive equilibrium?

(ii) Assume that because of technological development the LAC curve shifts down in such a way that the minimum average cost is equivalent to Rs. 12 and it takes place at output level 8. Determine how many firms will now operate in the market in long run?

E

Expert

Verified

Answer:

Long run equilibrium takes place if: AC = AR

Initially, AC is given as = Rs. 15

(At equilibrium condition, Quantity demanded = Quantity sold)

If P = AC = Rs. 15: Quantity Sold = 1200 units

If each firm is producing 10 units. Then no. of firms = 1200/10=120

If AC = Rs. 12

Then price (AR) = AC = Rs. 12, Quantity Sold= 1440 units.

If each firm is generating 8 units, Then no. of firms =1440/8 = 180

(i) Before change in technology: Quantity Sold = 1200 units and No. of firms = 120

(ii) After change in technology: Quantity Sold = 1440 units and No. of firms = 180

   Related Questions in Microeconomics

  • Q : Asymmetric Information-Efficiency of

    Asymmetric information is less difficult for the efficiency of laissez faire transactions whenever transactions: (i) Are voluntary and are predict to be repeated many times. (ii) Costs are relatively very high. (iii) Are regulated by the complex govt.

  • Q : Price ceiling set below equilibrium A

    A price ceiling set below equilibrium will raise the: (w) quantity supplied. (x) good’s opportunity cost to buyers. (y) sellers’ profits. (z) rate of excess supply. How can I solve my economics

  • Q : Spending pattern in Substitution Effects

    I have a problem in economics on spending pattern in Substitution Effects. Please help me in the following question. Even when your real income were held steady by adjusting for price modifications, your spending pattern would react to modifications in relative prices

  • Q : Constructing a model of Production

    Can someone please help me in determining the right answer from the following question. The three fundamental assumptions required to construct a model of the production possibilities frontier do not comprise: (1) Reducing marginal returns to producti

  • Q : Comparative statics and consumer demand

    Explain the methodological procedure called comparative statics.  What does this procedure imply regarding the nature of the consumer demand curve?

  • Q : Profit from predatory pricing In order

    In order for a firm to profit from predatory pricing: (w) the incumbent must fulfill the entire industry demand at a price below costs. (x) the cost of predation should be less than the profits incurred through driving out one’s rivals from the

  • Q : Corporate Taxes-Disadvantages of a

    One of the major disadvantages of the corporation is: (i) Double taxation of its gains. (ii) Its incapability to outlive the death of an owner. (iii) Its unlimited liability. (iv) Its inability to increase the financial resources.

  • Q : Pretax -posttax and transfer

    Refer to the following diagram. If line b represents the pretax and transfer distribution of income in the United States, we would expect the post-tax and transfer distribution to be: A) line a. B) line b, because taxes and transfers have no effect on income distribut

  • Q : Illegal price collusion Illegal price

    Illegal price collusion is probably when the market structure for an industry is: (1) monopolistic competition. (2) a monopoly. (3) an oligopoly. (4) pure competition. (5) contestable through exit and entry.

    Q : Maximizes total revenue by a monopolist

    A monopolist maximizes total revenue through producing where is: (w) marginal revenue = marginal cost [MR = MC]. (x) marginal revenue = 0. (y) demand is elastic. (z) demand is inelastic. How can I solve my