--%>

Types of elasticity of supply

Types of elasticity of supply:

There are five kinds of elasticity of supply:

1. Perfectly elastic supply:

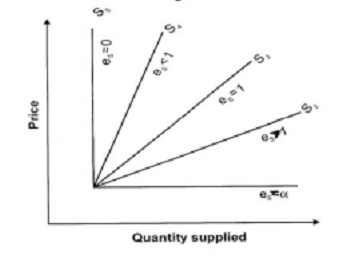
The coefficient of elasticity of supply is infinity. (i.e., es is ∞). For a little change or no alter in price, there will be an infinite amount of supply. (SS1 shown in figure below)

2. Relatively elastic supply:

The coefficient of elastic supply is always greater than 1(i.e., es > 1). Quantity supplied modifications by a bigger percentage than price. (SS2 shown in figure below)

3. Unitary elastic supply:

The coefficient of elastic supply is equivalent to 1 (i.e., es = 1). A change in cost will cause a proportionate modifications in quantity supplied. (SS3 shown in figure below)

4. Relatively inelastic supply:

The coefficient of elasticity is less than 1 (i.e., es < 1). Quantity supplied modifications by a lesser percentage than price. (SS4 shown in figure below)

5. Perfectly inelastic supply:

The coefficient of elasticity is equivalent to zero (i.e., es = 0).

The change in price will not bring around any modification in quantity supplied. (SS5 shown in figure below).
2214_types odf supply.jpg

   Related Questions in Microeconomics

  • Q : Other determinants that producers want

    In addition to price, what are the other determinants that producers want to sell?

  • Q : Words of Johann H. von Thünen about

    The theory about land derives its value primarily by how much its location conserves on transaction costs is attributable to: (a) Johann H. von Thünen. (b) Adam Smith. (c) Richard Cantillon. (d) David Ricardo. (e) Reverend Thomas Robert (“B

  • Q : Raising prices raises total costs for

    Total revenue at your fried hushpuppy stand has been declining currently. Your partner persevere that increasing hushpuppy prices will increase total revenue, although you believe only as fervently which lowering prices will produce more total revenue

  • Q : Determine price elasticity of demand An

    An approximate estimate of the price elasticity of demand is best computed by the absolute value of the formula: (1) change in P / change within Q. (2) % change in Q / % change in P. (3) % change in Q / % change in income. (4) % chang

  • Q : Definition of law of demand Definition

    Definition of law of demand: It is the claim that, other things equivalent, the quantity demanded of a good drops/falls whenever the price of the good increases.

  • Q : Supply law and it's factors State the

    State the Law of supply and explain the factors that affecting supply of commodity

  • Q : Hike within the minimum legal wage

    Labor market advises that a hike within the minimum legal wage from $5 per hour to $8 per hour will decrease: (1) the crime rate by 3,000. (2) national unemployment rates. (3) employment among unskilled workers by approximately 1,500 positions. (4) th

  • Q : Elucidate GNI per capita Elucidate GNI

    Elucidate GNI per capita?

  • Q : Jollies gained-Production occurs I have

    I have a problem in economics on Jollies gained-Production occurs. Please help me in the following question. The jollies gained whenever production takes place do not comprise utilities of: (i) Form. (ii) Possession. (iii) Place. (iv) Substance. (v) T

  • Q : Negative GDP gap A large negative GDP

    A large negative GDP gap implies: A) an excess of imports over exports. B) a low rate of unemployment. C) a high rate of unemployment. D) a sharply rising price level.