--%>

Example of determining new equilibrium price

As per such supply and demand curves for peanuts, there is the: (w) demand for peanuts has fallen. (x) price rises to P1 due to better peanut technology. (y) production of peanuts was initially Q0. (z) new equilibrium price of peanuts is P3.
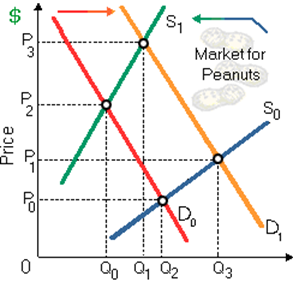
601_example of Equilibrium1.png

Please choose the right answer from above...I want your suggestion for the same.

   Related Questions in Microeconomics

  • Q : Minimum average costs Prohibition

    Prohibition Corporation could attain minimum average costs for its St. Valentine’s Day software when this produced: (1) 4 million copies. (2) 6 million copies. (3) 8 million copies. (4) 10 million copies. (5) 12 million copies.

    Q : Define linear consumption function

    Linear consumption function: It is a consumption function that is given on the basis of steady marginal propensity to consume. C = c + bY Here c = aut

  • Q : Decisions of market for loanable funds

    If considering the market for loanable funds, and the classical view of how interest is associated to people’s decisions to save is which: (w) interest income is the prime example of an unearned economic rent. (x) the primary reason for inequali

  • Q : Labor Unions-Sitdown Strikes Whenever

    Whenever unions and managers have failed to arrive at a collective bargaining agreement and workers reject to leave the production facility owned by firm, the union’s strategy is termed as: (i) Boycott or an embargo. (ii) Management lock-out. (i

  • Q : Production cost according to

    The global wide demand for bicycles would be least probable to be influenced if: (1) Rises in incomes in less developed countries permitted a lot of people to purchase automobiles. (2) Couch-potatoes start heeding their doctor’s suggestion to ex

  • Q : Pure competition and monopolistic

    Pure competition and monopolistic competition are: (1) polar opposites on the continuum of market structures. (2) the two market structures in that firms are pure quantity adjusters. (3) both characterized by an absence of barriers to long run entry a

  • Q : Marginal resource cost of labor For a

    For a gain maximizing competitive firm operating in the competitive labor market, the: (1) Marginal resource cost of the labor is similar to the wage rate. (2) Supply of the labor is perfectly inelastic. (3) Production quota is precisely proportional to the labor hire

  • Q : Signals of economic profits to

    Economic profits are: (1) signals which, for efficiency, more resources must be moved into an industry. (2) rewards to successful innovators. (3) capitalized as wealth when they can be expected over time. (4) a residual to a firm's owners for bearing

  • Q : Equilibrium GDP Provide solution of

    Provide solution of this question. If the MPC is .70 and gross investment increases by $3 billion, the equilibrium GDP will: A) increase by $10 billion. B) increase by $2.10 billion. C) decrease by $4.29 billion. D) increase by $4.29 billion.

  • Q : Problem on monoplists Suppose that the

    Suppose that the total cost curve for a monopolist is provided by TC = 3y2 + 800 and its marginal cost curve is given as MC = 6y.  Also assume it faces a market demand curve of py = 280 - 4y and marginal revenue curve of MR = 280 – 8y.