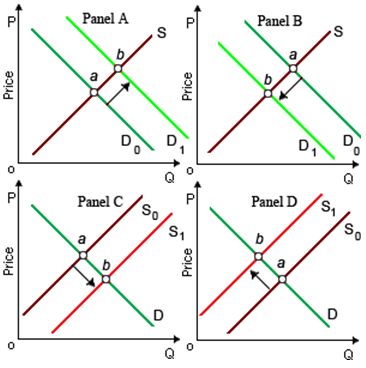
Equilibrium moves market reduce in supply
When equilibrium moves from point a to point b, the simple market experiencing a reduce in supply is demonstrated within: (w) Panel A. (x) Panel B. (y) Panel C. (z) Panel D. Can someone explain/help me with best solution about problem of economic...
When equilibrium moves from point a to point b, the simple market experiencing a reduce in supply is demonstrated within: (w) Panel A. (x) Panel B. (y) Panel C. (z) Panel D.
Can someone explain/help me with best solution about problem of economic...
I have a problem in economics on short run demand. Please help me in the following question. In short run, the demand mainly depends most on: (1) Supply. (2) Costs of production. (3) Consumer tastes and preferences. (4) Technology. (5) Resource access
Can someone help me in finding out the right answer from the given options. The marginal resource cost for the monopsonist in labor market which can’t wage discriminate: (i) Is perfectly elastic. (ii) Lies above the market supply of labor. (iii) Is perfectly ine
How you compare the average household income of the different countries?
Revenue: This refers to total money income from the sale of output.
Rises in per capita income in the United States would be most probable to reduce the: (i) Demands for lard, pinto beans, and utilized tires. (ii) Excesses in the federal govt. budget. (iii) Supply of untrained labor relative to skilled labor. (iv) Tot
In which market type, there is a requirement for selling or advertising costs? Answer: Beneath monopolistic competition, there is a requirement of selling costs sin
Moving from point d to point e beside demand curve D, the price elasticity of demands of DVDs of video games at equal: (a) 0.8. (b) one. (c) 1.10. (d) 1.25. (e) 2.50 Q : Short run for production I have a I have a problem in economics on Short run for production. Please help me in the following question. In short run for production: (1) Both variable and fixed costs exist. (2) Productive capacity might be adjusted. (3) Unprofitable firms shut down. (4) No fresh workers
I have a problem in economics on Short run for production. Please help me in the following question. In short run for production: (1) Both variable and fixed costs exist. (2) Productive capacity might be adjusted. (3) Unprofitable firms shut down. (4) No fresh workers
What is the formula for primary deficit? Answer: Primary deficit = fiscal deficit – interest payment.
When the rate of return onto an asset exceeds the interest rate: (1) its present value exceeds its price. (2) the market is moving away by equilibrium. (3) you should sell the asset as rapidly as possible. (4) economic rent is being r
18,76,764
1951218 Asked
3,689
Active Tutors
1419030
Questions Answered
Start Excelling in your courses, Ask an Expert and get answers for your homework and assignments!!